Learn / Deni & trust
Build trust when you offer deni
Credit keeps loyal customers—but awkward collection kills relationships when neither side trusts the number. Paying in bits is fine; the balance must stay clear.
The business problem
Regular customers buy on account. You know their face but not always their balance. When they pay partial, the notebook disagrees—and tomorrow’s credit decision is guesswork again.
Why it matters
Deni is a service that builds loyalty when records are clear. Unclear deni becomes conflict, lost stock without payment, and cash-flow holes you only notice at month end. Do not count debt payments as new sales—see Sales vs money in the till.
Common mistakes
- Anonymous credit—“that guy in the blue shirt”
- Updating balance without linking to the actual sale
- Extending more credit before checking what they already owe
- Avoiding collection because the record is embarrassing
Best practices
- Name + phone once; use the same customer every time
- Link each credit sale at checkout—stock leaves, balance updates
- Check “owes money” list before extending new deni
- Record partial payments the day they happen (do not wait for full settlement)
How F-Biz by Fayvad helps
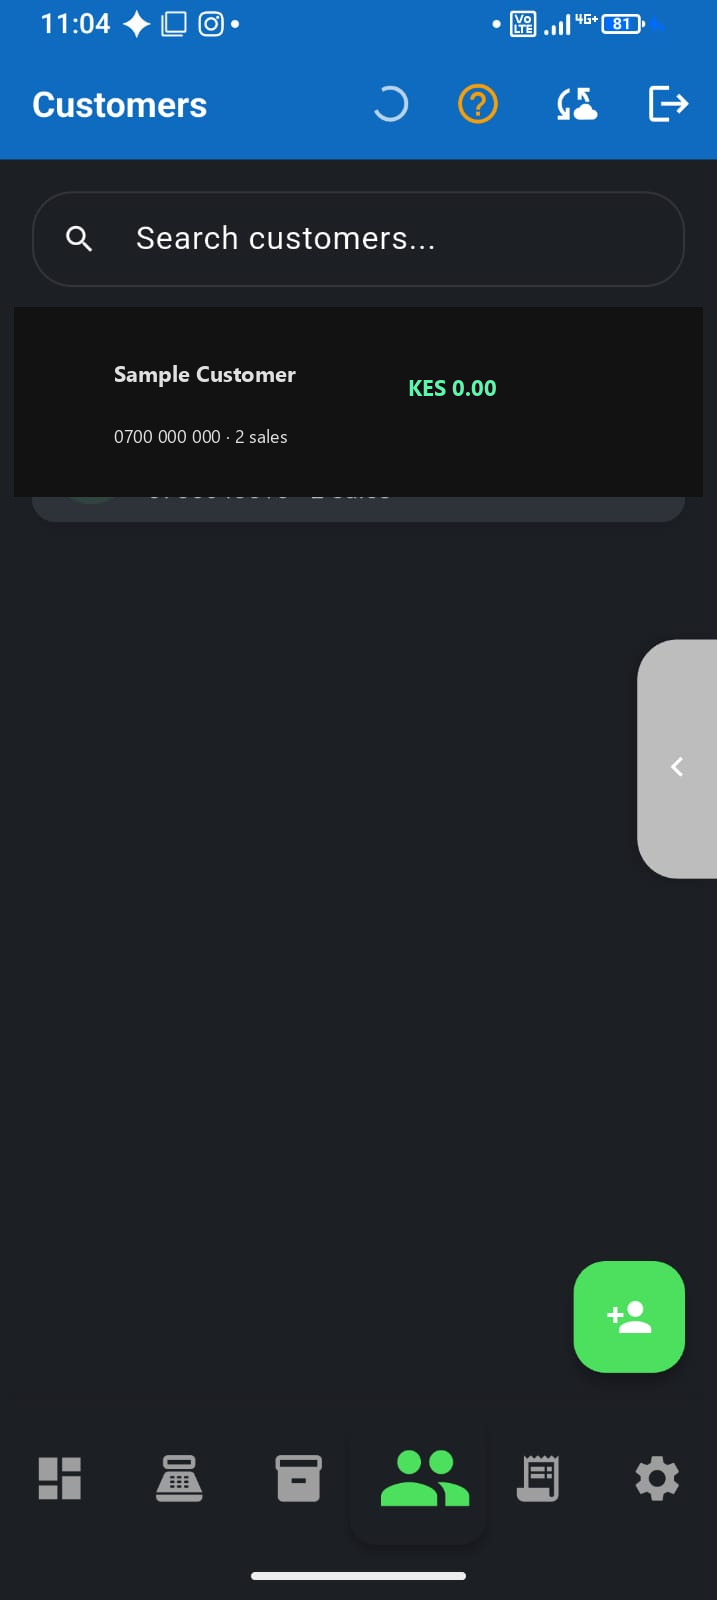
Credit sales tie to customers and reduce stock like cash. The customer list shows who owes what; filters surface open balances before you close. Record Payment accepts any installment; WhatsApp reminders stay professional when the number is agreed.
Action to take today
Add your three largest credit customers with correct balances. Before the next deni sale, open their record and confirm the number out loud with them.